2.1. Introduction
Brazil is one of the world’s largest economies and has a large domestic market. Despite its economic weight, its share of international trade in goods remains relatively modest when compared with the size of its economy and population.
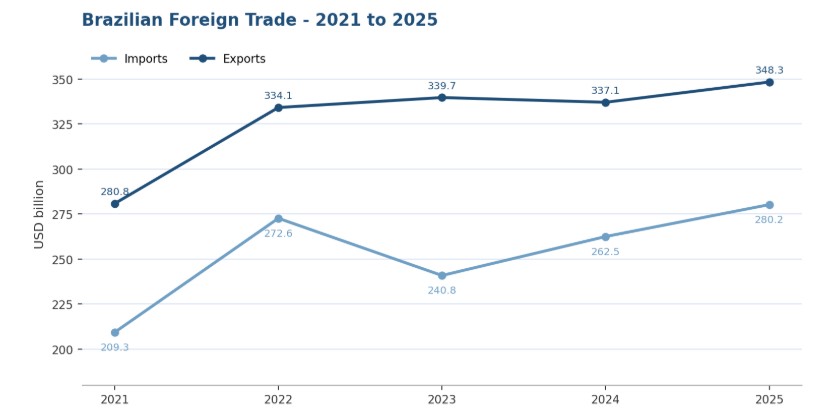
In 2025, Brazilian exports totaled USD 348.3 billion and imports USD 280.2 billion, resulting in total trade flows of USD 628.5 billion and a trade surplus of USD 68.1 billion. Brazil’s external trade performance remains strongly supported by commodities and agribusiness products, while the country also has significant value chains in aerospace, automotive, machinery, processed foods, chemicals, technology and other industrial sectors.
The number of exporting companies reached 29,818 in 2025, a new record. Even so, internationalization remains concentrated among a relatively small share of Brazilian companies, indicating significant room to expand the exporter base and develop new investment and international trade projects.
In recent years, Brazil has advanced the digitalization and integration of customs procedures. In 2026, implementation of the Single Import Declaration (Duimp) and the New Import Process is at an advanced stage, changing procedures, documentation and workflows for a wide range of transactions. At the same time, the Consumption Tax Reform has entered its transition period, requiring additional attention when preparing feasibility and landed-cost studies.
Source: MDIC/SECEX – Brazilian Foreign Trade Results – Consolidated Data; Exports and Imports by Company Tax Size.
2.2. Import Statistics
Brazilian imports resumed growth in 2025, reaching USD 280.2 billion. Recent developments underscore the importance of the Brazilian market for international suppliers of inputs, capital goods, components and finished products.
Source: MDIC/SECEX – Comex Stat / Consolidated Data, annual figures.
2.3. Export Statistics
Brazilian exports remained at a high level in 2025, totaling USD 348.3 billion. The result reflects the strength of agribusiness, mining, energy and food products, as well as the contribution of higher value-added industrial sectors.
Source: MDIC/SECEX – Comex Stat / Consolidated Data, annual figures.
Source: MDIC/SECEX – Comex Stat / Consolidated Data, annual figures.
2.4. Regulatory and Administrative Framework
International trade in Brazil operates within a detailed regulatory framework. Before beginning import or export operations, a company must address customs authorization, tariff classification, administrative treatment, requirements imposed by competent authorities, commercial and logistics documentation, customs clearance and taxation.
The Single Foreign Trade Portal and Siscomex centralize a substantial portion of registrations and controls. The Brazilian Federal Revenue Service, the Secretariat of Foreign Trade and competent regulatory authorities use these systems to receive information, assess risks, issue authorizations and monitor transactions.
Specialized Support
Given the complexity of the Brazilian system, companies – particularly foreign companies – are advised to rely on professionals and firms specialized in international trade, such as trading companies, customs brokers, freight forwarders and consultants. This support helps structure transactions correctly, reduce risks, prevent documentation and tax errors, assess logistics and tax alternatives, and improve predictability of costs and lead times.
For foreign companies entering the Brazilian market, such support is particularly valuable in defining the appropriate import or export model, understanding regulatory requirements, assessing applicable incentives and benefits, and designing an operating model suited to local conditions.
Duimp in 2026
In 2026, Duimp is already mandatory for a broad range of transactions, in accordance with the phased discontinuation schedule for the Import Declaration (DI). The applicability of Duimp, LPCO and other requirements must be checked on a transaction-by-transaction basis in the Single Foreign Trade Portal and Siscomex Notices.
Main Steps and Documents
1. Licenses, Permits, Certificates and Other Documents (LPCO)
Certain products may be subject to sanitary, agricultural, metrological, environmental, technical or safety controls. Requirements depend on the NCM tariff classification, product attributes, the purpose of the transaction and the competent regulatory authority.
2. Customs Declaration
The transaction is registered electronically in Siscomex/the Single Foreign Trade Portal, including tariff classification, value, origin, destination, tax treatment and other applicable information.
3. Customs Clearance
The Brazilian Federal Revenue Service reviews the declaration and applies its risk-management procedures. Shipments may be routed to the Green, Yellow, Red or Gray channels depending on the level of inspection required.
4. Taxation
Commercial imports may be subject to Import Duty (II), IPI, PIS/Pasep-Import, Cofins-Import, ICMS and other applicable charges. In 2026, these rules coexist with the initial transition phase toward CBS and IBS.
5. Logistics Documentation
This normally includes the Commercial Invoice, Bill of Lading (B/L) or Air Waybill (AWB), Packing List and Certificate of Origin, when applicable.
6. Controls and Inspections
Depending on the nature of the goods, controls by the Brazilian Federal Revenue Service and competent regulatory authorities may apply, including documentary or physical inspections.
Source: Brazilian Federal Revenue Service / Siscomex – Administrative Treatment for Imports; Duimp/DI implementation schedules.
2.4.1. Key Players in International Trade
The Importer / Exporter
To engage in international trade, companies must be authorized to operate in the Integrated Foreign Trade System (Siscomex). Authorization is granted by the Brazilian Federal Revenue Service (RFB), currently through the Habilita System within the Single Foreign Trade Portal. The Habilita System automatically determines the applicable authorization category and, where relevant, the operating limit, based on the applicant’s profile and estimated financial capacity.
1. Express Category
Applicable to specific situations established by regulation, such as certain publicly held corporations, public companies and mixed-capital companies. Under this category, no operating limit applies to imports or exports.
2. Limited Category
Applies to companies whose estimated financial capacity for imports is up to USD 150,000 in each consecutive six-month period. This category is divided into two brackets:
- Limited 50,000: estimated financial capacity of up to USD 50,000;
- Limited 150,000: estimated financial capacity above USD 50,000 and up to USD 150,000.
3. Unlimited Category
Applies to companies whose estimated financial capacity exceeds USD 150,000 in each consecutive six-month period. There is no predetermined operating limit, but transactions must remain consistent with the financial capacity recognized by the Brazilian Federal Revenue Service.
The authorization remains active provided there is activity within the regulatory period. Inactivity for more than 12 months may result in automatic deactivation. When the intended volume exceeds the assigned estimate, the company may request a review of its financial capacity in accordance with the rules and criteria established by the Brazilian Federal Revenue Service.
The documentation required for a review varies according to the circumstances of each case. Corporate documents, financial statements, bank transactions, capital contributions and other evidence of economic and financial capacity may be assessed. Therefore, there is no single checklist applicable to every case.
Source: Brazilian Federal Revenue Service – Authorization through the Habilita System; Review of Estimated Financial Capacity.
2.4.2. Trading Companies
Trading companies and specialized importers play an important role in structuring international transactions, particularly when a client intends to outsource customs, tax, logistics and documentation coordination.
For exports, companies commonly use a trading company when they are not yet authorized in Siscomex or when they choose to outsource the execution of the transaction. Under this model, the trading company formally carries out the export in its own name, subject to the applicable rules, while the contracting company may preserve the tax benefits associated with exports, depending on the nature of the transaction and the relevant tax legislation.
For imports, two main indirect import models should be highlighted:
- Importation on Behalf of and for the Account of a Third Party (Conta e Ordem): the importer conducts customs clearance in its own name as a service provider, using the purchaser’s funds. The purchaser is identified and linked to the transaction in accordance with Siscomex rules.
- Importation by Order (Encomenda): the importer uses its own funds to purchase the goods abroad and subsequently resells them to a predetermined ordering company.
For legal entities, the importer and the purchaser/ordering company must comply with the authorization and linkage requirements established by the Brazilian Federal Revenue Service. The contractual and operational structure must be formalized before the import declaration is registered.
Source: Brazilian Federal Revenue Service – Importation on Behalf of and for the Account of a Third Party and Importation by Order.
2.4.3. Customs Brokers
A customs broker is a qualified professional authorized to represent importers and exporters before customs authorities within the powers granted. The broker assists with the filing and monitoring of declarations, document review, responses to official requirements, inspection follow-up and customs clearance support.
The customs broker may also provide technical support on tariff classification, administrative treatment and risk identification, without replacing the legal responsibilities of the importer or exporter.
During customs clearance, the inspection channel may be selected randomly or based on risk-management criteria such as the importer’s history, product type, origin of the goods, declared values and any previous outstanding issues. The customs broker plays an essential role in mitigating risks, responding promptly to requirements and contributing to the smooth flow of the transaction.
2.4.4. Freight Forwarders
A freight forwarder coordinates international logistics from origin to destination, including freight procurement, cargo consolidation, issuance or management of transport documents, and coordination with terminals, carriers and logistics operators. Depending on the scope, the freight forwarder may also coordinate insurance, warehousing and ancillary services.
2.4.5. Customs Authorities
The Brazilian Federal Revenue Service is responsible for customs control, enforcement, collection of federal taxes levied on imports and combating unlawful practices. Its activities include document review, channel selection, physical inspection, issuance of requirements, post-clearance review and application of penalties where appropriate.
Brazilian exports receive favorable tax treatment compared with domestic sales, through rules on immunity, non-incidence, suspension, preservation of tax credits or tax relief depending on the tax and regime involved. Imports, by contrast, require a detailed assessment of the tax burden and logistics charges.
Imports, however, may be subject to federal taxes such as Import Duty (II), IPI, PIS/Pasep-Import and Cofins-Import, as well as the state-level ICMS and additional charges applicable to the transaction, such as AFRMM for maritime transport. The effective tax burden depends on tariff classification, origin, destination state, the company’s tax regime, import model and any applicable special regimes or incentives. The complexity of the system requires appropriate tax and operational planning.
Strikes, work-to-rule actions or contingencies affecting public authorities and terminals may delay cargo release and increase warehousing costs. Contracts and logistics planning should therefore provide adequate operational contingencies.
2.4.6. Regulatory Authorities and Other Governmental Entities
Depending on the product, a transaction may require registrations, certifications, LPCO documentation or approval from specialized authorities. The main authorities include:
- ANVISA – Brazilian Health Regulatory Agency: medicines, medical devices, cosmetics, personal-care products, food and other products subject to sanitary surveillance.
- MAPA – Ministry of Agriculture and Livestock: animal- and plant-origin products, agricultural inputs and phytosanitary controls, among others.
- ANATEL – National Telecommunications Agency: telecommunications products and equipment subject to type approval and other technical requirements.
- INMETRO – National Institute of Metrology, Quality and Technology: mandatory certification and metrological/technical controls applicable to various products.
- IBAMA – Brazilian Institute of Environment and Renewable Natural Resources: products and transactions subject to environmental controls.
- ANP – National Agency of Petroleum, Natural Gas and Biofuels: products and activities regulated in the oil, natural gas and biofuels sector.
Requirements should not be assumed solely from the commercial description of a product. Validation should consider the NCM classification, product attributes, intended use, specific legislation and the administrative treatment in force in the Single Foreign Trade Portal.
2.5. Logistics
2.5.1. Introduction
With approximately 8.5 million km², Brazil is continental in scale. This creates substantial market opportunities but also significant transportation, warehousing and distribution challenges.
Brazil’s logistics matrix remains heavily dependent on road transport, although ports, railways, airports and multimodal corridors have received significant investment in recent years. In 2025, Brazilian ports handled 1.4 billion metric tons, an all-time record.
- Uneven road infrastructure and high dependence on trucking.
- Multimodal integration remains limited in several corridors.
- Traffic congestion and urban restrictions in major metropolitan areas.
- High logistics costs in certain supply chains and regions.
- Security risks, particularly cargo theft on certain routes.
- Climate and geographic impacts on routes and lead times.
Source: Ministry of Ports and Airports / ANTAQ – 2025 port throughput; Ministry of Transport – Federal Highways.
2.5.2. Air Transport
Brazil’s aviation sector is regulated by the National Civil Aviation Agency (ANAC) and operates under national and international safety standards. Airport infrastructure is managed by a combination of private concessionaires, Infraero and other operators, depending on the airport.
In 2025, Brazilian airports handled approximately 129.59 million passengers, an all-time record. For international trade, the main hubs include Guarulhos (GRU), Viracopos/Campinas (VCP), Galeão (GIG), Curitiba (CWB) and Confins (CNF), as well as other customs-enabled airports with significant operations.
For air cargo, imports and exports may be processed through several airports across Brazil. Customs clearance is available at customs-enabled airports with suitable infrastructure, including Guarulhos (GRU), Viracopos/Campinas (VCP), Galeão (GIG), Confins (CNF), Curitiba (CWB), Florianópolis (FLN), Recife (REC), Porto Alegre (POA) and Manaus (MAO), among others. Airport selection should take into account route availability, frequency, cargo facilities, regulatory requirements, transit time and the total cost of the transaction.
Zurich Airport Brasil operates the airports of Florianópolis, Vitória, Macaé and Natal. Air freight is particularly suitable for urgent, perishable or high-value goods, as well as shipments with specific time or security requirements.
Source: ANAC – 2025 Management Report; Zurich Airport Brasil – About Us.
2.5.2.1. Main Brazilian Airports
| Airport | Strategic role |
| São Paulo/Guarulhos (GRU) | Brazil’s main international gateway for passengers and an important cargo hub. |
| Viracopos/Campinas (VCP) | Strong specialization in air cargo, express courier services and industrial imports. |
| Rio de Janeiro/Galeão (GIG) | Relevant international hub for Southeast Brazil and for cargo and passenger operations. |
| Curitiba (CWB) | Important airport in Southern Brazil, with international operations and cargo-handling infrastructure. |
| Confins/Belo Horizonte (CNF) | Regional hub with international operations and growing logistics importance. |
2.5.3. Waterway Transport
Waterway transport is essential to Brazilian foreign trade, particularly for containers, agricultural and mineral bulk cargo, fuels, chemicals and industrial cargo. In 2025, Brazil’s port system reached a record level of throughput.
| Region | Key ports |
| Southeast | Santos (SP), Vitória (ES), Rio de Janeiro (RJ) |
| South | Paranaguá (PR), Rio Grande (RS), Itajaí (SC), Itapoá (SC), Navegantes (SC) |
| Northeast | Suape (PE), Salvador (BA) |
| North | Manaus (AM), Belém (PA) |
The advantages of this mode include high capacity, lower unit costs for large volumes and direct access to international markets. Challenges include landside access bottlenecks, the need to expand capacity at certain terminals, intermodal integration and variability in lead times depending on the port, terminal, shipping line and seasonality.
Source: Ministry of Ports and Airports / ANTAQ – Brazilian Ports 2025.
2.5.4. Road Transport
Road transport is the primary mode for domestic freight distribution in Brazil. The federal highway network comprises approximately 75,800 km, of which around 65,400 km are paved. By the end of 2025, approximately 15,800 km were under active federal concessions.
- Door-to-door flexibility and extensive geographic reach.
- Relative speed over short and medium distances.
- Significant fuel, toll and maintenance costs.
- Uneven infrastructure quality across corridors and regions.
- Need for risk management, tracking and insurance on certain routes.
Source: Ministry of Transport – Federal Highways; ANTT/TCU – federal concessions.
2.5.5. Rail Transport
Brazil’s rail system is concentrated on the transport of large volumes of agricultural commodities, minerals and fuels. Despite longstanding limitations in coverage, integration and capacity, new concession, renewal and expansion projects aim to increase rail’s share of the national logistics matrix.
- High capacity for large volumes.
- Greater energy efficiency than road transport over long distances.
- Lower emissions intensity per ton transported on certain corridors.
- Need for greater integration with ports, terminals and highways.
2.6. Import Cost Structure
Importing into Brazil involves taxes, fees and logistics costs that directly affect the landed cost of the product. The composition varies depending on the product, NCM classification, origin, import model, importer’s tax regime, destination state, transport mode, terminal and any applicable special regimes.
- Import Duty (II)
- Tax on Industrialized Products (IPI)
- PIS/Pasep-Import and Cofins-Import
- ICMS
- AFRMM, when applicable to waterway transport
- Warehousing, terminal handling, inland transport, customs clearance and other operating expenses
- CBS and IBS within the Tax Reform transition, according to the applicable schedule
2026 is a Transition Year
Landed-cost studies should clearly state whether a scenario reflects the rules actually in force in 2026 or projections for 2027 onward. Combining assumptions from different periods may distort cost comparisons.
2.6.1. Import Duty (II)
Import Duty (II) is a federal tax levied on the entry of foreign goods. The applicable rate depends on tariff classification, origin, trade agreements, special regimes and trade-policy measures. As a general rule, Import Duty does not generate a tax credit for the importer.
The Simplified Taxation Regime for international shipments should be treated separately from regular commercial imports. Under the Remessa Conforme Program, the rules applicable in 2026 vary according to value, the nature of the sender and recipient, and the platform’s qualification.
Source: Brazilian Federal Revenue Service – Taxation of International Shipments.
2.6.2. Tax on Industrialized Products (IPI)
IPI is a federal tax levied on industrialized products. On imports, it is charged at customs clearance. Rates are established in the TIPI schedule and vary according to tariff classification.
The availability of tax credits depends on the taxpayer’s tax status, the nature of the transaction and the applicable legislation. It should not be assumed solely on the basis of the Actual Profit or Presumed Profit corporate income tax regime.
The Tax Reform provides for a substantial reduction in IPI beginning in 2027, subject to exceptions related to the Manaus Free Trade Zone and other specific rules.
2.6.3. PIS and Cofins on Imports
PIS/Pasep-Import and Cofins-Import remain applicable in 2026. Rates and entitlement to tax credits depend on the product, the legislation and the applicable assessment regime. For certain goods listed by law, the additional Cofins-Import rate is 0.6 percentage point in 2026 and will be 0.4 percentage point in 2027.
PIS and Cofins will be replaced by CBS in 2027. Accordingly, 2026 should be treated as a testing and adaptation period, rather than the year in which these contributions are abolished.
Source: Law No. 14,973/2024; Brazilian Federal Revenue Service – Consumption Tax Reform.
2.6.4. ICMS
ICMS is a state-level tax that remains in force during the Tax Reform transition. The rate and calculation method depend on the state, product, transaction and applicable tax regime. Certain states maintain differentiated tax treatments for imports, subject to their own requirements.
Taxpaying companies may be entitled to ICMS credits in the circumstances provided by law. The analysis should consider the entire transaction flow, including entry, subsequent sale, destination of the goods and any special regime used.
2.6.5. Brazilian Tax Reform
Constitutional Amendment No. 132/2023 and supplementary legislation established a broad reform of consumption taxation. The new model progressively replaces PIS, Cofins, ICMS and ISS with CBS and IBS, and also introduces the Selective Tax (IS).
| Period | Main effects |
| 2026 | Test year: CBS at 0.9% and IBS at 0.1%, with offset or waiver mechanisms conditional on compliance with applicable ancillary obligations. |
| 2027 | Abolition of PIS/Cofins; full implementation of CBS; reduction of IPI to zero for most products, subject to exceptions; introduction of the Selective Tax. |
| 2027-2028 | IBS in its initial phase at 0.1%; CBS adjustments to offset the IBS component, as provided by law. |
| 2029-2032 | Gradual transition from ICMS and ISS to IBS. |
| 2033 | Full implementation of the new consumption-tax model. |
Benefits and incentives linked to ICMS and ISS will be gradually reduced as these taxes are replaced by IBS, subject to the compensation rules, exceptions and funds established by law.
Source: Brazilian Federal Revenue Service – Understanding the Consumption Tax Reform; CGIBS – IBS/CBS implementation.
2.7. International Trade Incentives
2.7.1. Export Incentives
Brazilian tax policy seeks to avoid exporting domestic taxes by preserving mechanisms for tax relief, non-incidence, immunity, and the maintenance or recovery of tax credits depending on the tax and applicable regime. This supports the international competitiveness of Brazilian products.
In addition to traditional mechanisms, 2026 includes newer instruments designed to finance and support exports, including the Foreign Trade Operations Guarantee Fund (FGCE) and the Acredita Exportação program, which is primarily aimed at micro and small enterprises under the conditions established by law.
Source: MDIC – Acredita Exportação; MDIC/Ministry of Finance/ABGF – FGCE.
2.7.2. Import Incentives
Some Brazilian states maintain special regimes or differentiated ICMS tax treatments designed to attract operations, investment and distribution centers. Requirements vary significantly among states and programs and may involve a local establishment, the import model, destination of the goods, additional payments and ancillary compliance obligations.
At the federal level, the Ex-Tarifário regime remains relevant for certain capital goods and information technology and telecommunications goods for which there is no equivalent domestic production, subject to the criteria and procedures in force.
Recommended Assessment
Tax incentives should not be assessed in isolation. The most appropriate structure results from the combined analysis of tax burden, tax credits, logistics costs, transit time, warehousing, working capital, the company’s tax regime and customer locations.
2.8. Corruption and Compliance
Corruption remains an institutional risk to be considered when operating in Brazil, as in other markets. For foreign companies, the recommended approach is to establish clear compliance controls, segregation of duties, document traceability, partner due diligence and internal reporting channels.
The digitalization of international trade, with extensive use of electronic systems, auditable records and data integration, helps increase transaction traceability and reduce unnecessary face-to-face interactions.
In Transparency International’s 2025 Corruption Perceptions Index, Brazil scored 35 out of 100 and ranked 107th among 182 countries and territories. The index measures perceptions of public-sector corruption and should be interpreted as a comparative benchmark, rather than a direct measure of occurrence in specific transactions.
Source: Transparency International – Corruption Perceptions Index 2025 – Brazil.
2.9. A Foreign Perspective on Brazil
2.9.1. Is Brazil a Low-Cost Country?
A common perception among foreign visitors is that certain services and consumer items in Brazil may be less expensive than in European markets. However, this perception does not necessarily reflect the actual cost of operating a business in the country.
Taxation, employment-related costs, logistics, cost of capital, infrastructure and regulatory complexity can significantly increase the cost of doing business. Market-entry decisions should therefore be preceded by an assessment of feasibility, corporate structure, location and supply chain.
2.9.2. Mobility and Transportation
Mobility varies considerably across regions. Major urban centers have extensive air infrastructure and significant road connectivity, but congestion and internal distances can increase travel times. In remote areas, infrastructure may be limited and require more careful planning.
2.9.3. Products and Export Challenges
Brazil is one of the world’s leading exporters of agricultural, mineral and energy commodities and also has internationally competitive companies in industrial sectors such as aerospace, processed foods, automotive parts, machinery and technology. Even so, logistics costs, exchange-rate volatility, financing, taxation and regulatory requirements may constrain the competitiveness of higher value-added products.
2.9.4. Product Pricing
Pricing in Brazil still reflects the complexity of the current tax system. In 2026, this structure formally entered the transition to CBS and IBS. Over the coming years, companies will need to operate under coexisting rules and progressively adapt their systems, contracts and pricing models.
2.9.5. Location Considerations
São Paulo remains the country’s principal economic and financial center, but other regions also offer competitive industrial, technology and logistics hubs. Location decisions should consider infrastructure, proximity to customers and suppliers, workforce availability, access to ports and airports, ICMS regimes during the transition period and operating costs.
2.9.6. Size of the Country
Brazil covers approximately 8.5 million km², more than 200 times the area of Switzerland. This scale makes it impractical to treat the country as a geographically homogeneous market. Commercial and logistics strategies generally need to prioritize specific regions and, for larger operations, may require multiple distribution centers or regional partners.
2.9.7. Culture
Brazil’s cultural diversity reflects Indigenous, African, European, Asian and Latin American influences. There are notable regional differences in habits, accents, cuisine, negotiation styles and consumer behavior. Foreign companies that adapt their communication, customer approach and commercial strategy to local characteristics tend to build stronger relationships.
2.9.8. Language
Portuguese is Brazil’s official language and differs in important respects from European Portuguese. Commercial and technical materials should be adapted to Brazilian Portuguese, particularly when addressed to customers, distributors and regulatory authorities.
In the EF English Proficiency Index 2025, Brazil scored 482 and ranked 75th globally, in the low-proficiency category. This reinforces the importance of providing materials and commercial support in Portuguese to improve effectiveness in the market.
Source: EF English Proficiency Index 2025 – Brazil.
2.9.9. The Brazilian Domestic Market
Brazil has a population of more than 200 million and one of the world’s largest consumer markets. However, income, purchasing power and consumption patterns vary significantly across regions and socioeconomic groups.
For foreign companies, market size should be assessed together with customer segmentation, distribution channels, price positioning, local competition, regulatory requirements and market-entry costs. Sectors such as healthcare, technology, industry, education, mobility, energy and digital commerce offer significant opportunities, but require tailored strategies.
2.10. Trade Agreements and International Integration
Brazil is a member of Mercosur, together with Argentina, Paraguay, Uruguay and Bolivia. Through the bloc, Brazil participates in trade agreements with various partners and regions and is also a member of the World Trade Organization (WTO).
- Mercosur-European Union: the Partnership Agreement was signed on January 17, 2026. The Interim Trade Agreement began to apply provisionally on May 1, 2026, with tariff-reduction schedules in effect while approval and ratification procedures continue.
- Mercosur-EFTA: the agreement, which includes Switzerland, was signed on September 16, 2025. As of August 2026, it remained subject to the preparatory and ratification procedures required for entry into force.
- Other agreements: Mercosur maintains trade arrangements with partners such as Israel, Egypt, India and several Latin American countries, each with specific rules and tariff preferences.
The use of tariff preferences depends on tariff classification, rules of origin, documentation and the applicable schedule. For foreign companies, trade-agreement analysis should form part of the market-entry and landed-cost assessment, particularly where alternative production origins are available.
Source: Siscomex – Mercosur-European Union Agreement; Siscomex – Mercosur-EFTA Agreement.
Final Considerations
The Brazilian market combines scale, sector diversity and significant opportunities with an operating environment that requires technical preparation. The evolution of the Single Foreign Trade Portal, migration to Duimp, the tax transition and new trade agreements are progressively changing how companies structure transactions and assess costs.
- Validate tariff classification and administrative treatment before shipment.
- Select the import model and tax structure in an integrated manner.
- Consider logistics and tax costs by state, rather than nominal tax rates alone.
- Clearly distinguish the rules in force in 2026 from future Tax Reform scenarios.
- Reassess landed cost and contracts as CBS, IBS and other changes take effect.
- Use specialized support to reduce risks, improve predictability and identify operational alternatives.
Authors: Victor Albert Batista da Silva, Lucilene Aparecida Queiroz and Milane Brixi
FORVM Comércio Exterior Ltda.
Rua Jaroslau Clemente Pesch, 50 – Block B – Floresta
89211-493 Joinville, Santa Catarina, Brazil
Site: https://www.forvm.com.br/
Phone: +55 (47) 3433-0641
Phone: +55 (47) 99766-0080
Email: [email protected]
Email: [email protected]
Update Note
Regulatory and tax information verified through September 2026. Legislative, operational and system changes may occur after this date. For investment or import decisions, product- and transaction-specific validation is recommended.