I. INTRODUCTION
Electrical energy is one of the main inputs for the Brazilian industry, and the safety of its supply and its cost are determining and essential factors for the competitiveness of Brazilian products.
According to estimates, factories account for approximately 35,9% of the country’s electrical energy consumption (base year 2024).
I.I. THE BRAZILIAN ELECTRICAL INDUSTRY
In Brazil, the electrical industry is divided into generation, transmission, distribution, and trading, and its regulation is the responsibility of the Brazilian Electricity Regulatory Agency (ANEEL).
- Generation: is the segment of the electricity industry responsible for producing electrical energy and feeding it into the transportation systems (transmission and distribution) for it to reach consumers.
- Transmission: is the segment that transports large amounts of energy from the generating plants. Transmission is responsible for delivering energy to the distributors.
- Distribution: receives the energy from the transmission system and distributes it at retail to consumers.
- Trading: Trading companies purchase energy by means of bilateral contracts in the free environment, and they may resell this energy to free or special consumers or to other traders. They may also resell to distributors, in this case only in auctions conducted in the regulated environment.
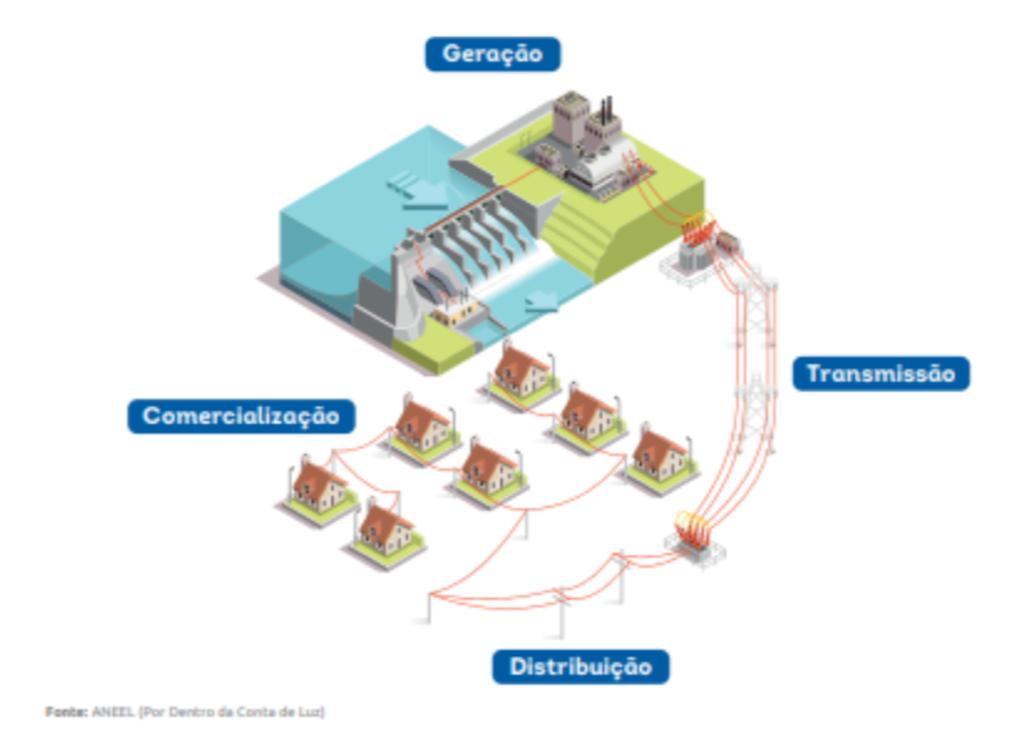
Legend (clockwise):
Generation
Transmission
Distribution
Trading
Source: ANEEL (Por Dentro da Conta de Luz)
In addition, the Electrical Sector is formed by the National Interconnected System (SIN), a large network, extending over a large part of the Brazilian territory, congregating generation systems and an electrical transmission grid, divided into 4 subsystems: Northeast, Southeast/Central West, South, and North.
FOTO 1
Source: ONS – Operador do Sistema Nacional
Finally, the organization chart below presents the institutions and organization of the Brazilian sector responsible for its governance and organization:
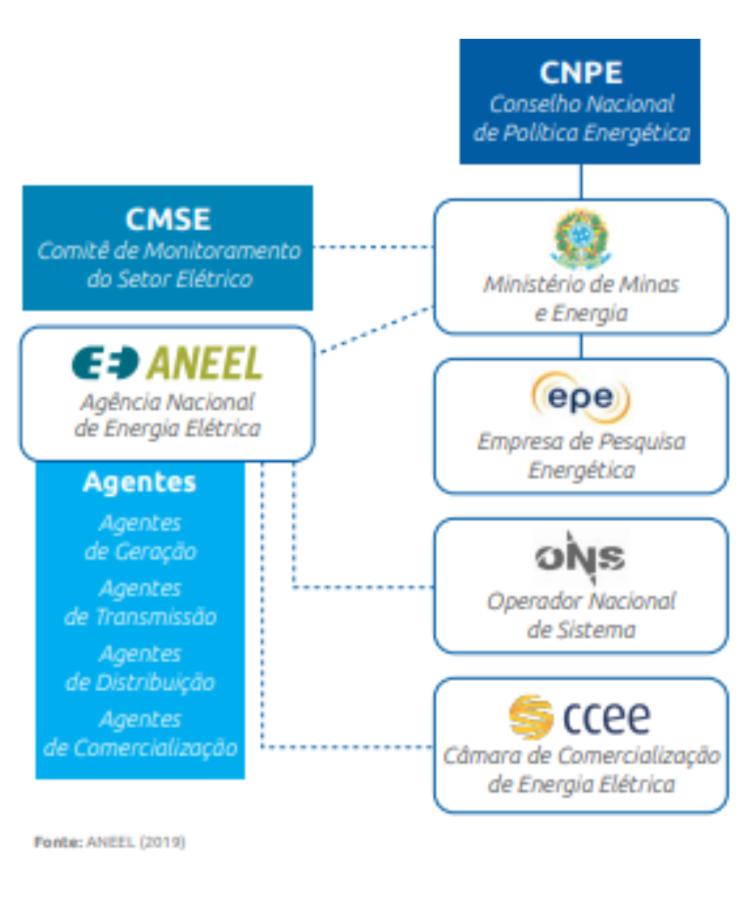
Legend:
Column 1
CMSE – Electrical Industry Monitoring Committee
ANEEL – Brazilian Electrical Energy Agency
Agents
Generation Agents
Transmission Agents
Distribution Agents
Trading Agents
Column 2
Ministry of Mines and Energy
EPE – Empresa de Pesquisa Energética [Energy Research Company]
ONS – National System Operator
CCEE – Electric Energy Trading Chamber
Source: ANEEL (2019)
I.I.1 Contracting Environments – Energy Markets
The Electrical Industry is divided into two energy contracting environments, to wit: (i) captive market and (ii) free market.
- Captive Market or Regulated Contracting Environment – ACR: in the captive market, consumers may only purchase energy from local distributions that hold a concession to sell energy in that region. The captive market is estimated to account for 57% of the total consumption of energy in Brazil (base year 2024).
- Free Market or Free Contracting Environment – ACL: in the free market, consumers purchase energy directly from the generators or traders, through bilateral contracts with freely negotiated conditions, such as price, term, and volume. The free market is estimated to account for 43% of the total consumption of energy in Brazil and for 85.5% of industrial consumption (base year 2024).
Legislative update: the universal opening of the free energy market was structured by Laws No. 15,235/2025 (conversion of Provisional Measure No. 1,300/2025) and, mainly, Law No. 15,269/2025 (conversion of Provisional Measure No. 1,304/2025). Law No. 15,235/2025 also introduced, in parallel, the expansion of the Social Tariff and other sectoral adjustments. The implementation schedule was regulated by Decree No. 13,097/2026: industrial and commercial low-voltage consumers may exercise free choice of supplier as from 25 November 2027, and the remaining consumers (including residential) as from 25 November 2028 (see Section IV).
I.I.2. Functioning of the Energy Market – Summary Scenario
The energy market is complex and there are a number of agents that act in the various phases of the electricity circulation chain, from generation to consumption, as shown above.
The most common agents are generators, transmitters, distributors, traders, and consumers. There are two energy contracting environments, the regulated and the free market.
Generators may operate in both environments, and they are responsible for producing electrical energy.
Transmitters transport electrical energy in high voltage to the consumer centers, but do not sell energy. Thus, they do not operate in either market.
Distributors operate only in the regulated/captive market, they lower the voltage and supply electrical energy to consumers. They sell and physically deliver energy to captive consumers and only physically deliver the energy to free consumers.
Traders operate in the free contracting environment (free market) and may engage in a variety of activities: customer representation, management, intermediation, and purchase and sale of energy.
Consumers are the purchasers of electrical energy, and they may be divided into captive and free consumers. Captive consumers only purchase energy from the distributors, through the electrical grid to which they are connected. Free consumers may purchase energy from the generators or traders, to which they pay for the price of energy, but continue to pay the distributors for use of the electrical grid.
It should also be noted that system operation is coordinated by the National System Operator (ONS) and that the accounting and settlement of energy purchase and sale transactions are carried out by the Electric Energy Trading Chamber (CCEE).
I.I.3. Composition of the electrical energy tariff
The electrical energy tariff shall guarantee the supply of energy with quality and ensure the service providers sufficient revenue to cover efficient operational costs and remunerate investments required to expand capacity and guarantee the supply to individuals and legal entities.
The electrical energy tariff is composed of the amounts of investment and technical operations carried out during the generation, transmission, distribution, and trading processes, in addition to the sectorial charges and taxes (ICMS, PIS/COFINS, and Public Lighting Contribution), as explained in further detail below.
A.1. Costs relating to Electrical Energy Supply
With respect to the costs involved in the supply of energy, which are assessed for composition of the tariffs, we note different costs, which relate to:
- purchase of electrical energy (Purchased Energy) – the value of the generation of energy purchased by the distributors for resale to their consumers is determined in public auctions, which ensures transparency of cots, competitiveness, and best prices;
- use of the distribution system and use of the transmission system (Transport of energy to the consumer units (transmission and distribution) encompassing the specific tariffs (TUST and TUSD) that remunerate the use of infrastructure – The costs involved in the transmission of electrical energy are those related to the transport of energy from the generating units to the distribution systems, and they are composed of the following items:
-
- use of the transmission facilities classified as Basic Grid, Border Basic Grid, or Other Transmission Facilities (DIT) of shared use,
- use of the distribution facilities,
- connection to DIT of exclusive use,
- connection to the distribution grids,
- transport of the energy originating from Itaipu to the point of connection to the Basic Grid, (vi) use of the Basic Grid by the Itaipu plant, and
- use of the transmission system by the power plants connected at a voltage level of 88 kV or 138 kV.
The costs of the distribution activity (entirely managed by the distributor), in turn, are costs related to the investments made by it, in addition to the depreciation quota of its assets and the regulatory remuneration.
A.2. Sectorial Charges
Despite being established by laws to enable the implementation of public policies in the Brazilian electrical sector, their amounts are set forth in resolutions or orders of the Brazilian Electrical Energy Agency (ANEEL) and are paid by the distributors through electricity bills. There are approximately 18 sectorial charges and fees that are therefore, included in the electrical energy tariff. Among these 18 charges, the Incentive Program for Alternative Sources (PROINFA) and the Energy Development Account (CDE) stand out, with the latter being the most significant in terms of relevance and value.
PROINFA (Law No. 10,438/2002) aims to increase the participation of renewable sources, such as Small Hydroelectric Plants, wind power and biomass thermal plants, in electricity production. The cost of these projects is divided into monthly quotas collected by distributors, transmission companies and licensed cooperatives. The calculation of the quotas is based on the Annual PROINFA Plan (PAP) prepared by ENBPar and submitted to ANEEL. The amounts are paid by all free and regulated consumers of the National Interconnected System (SIN), except those classified as low-income. For 2026, the PROINFA sharing tariff was set at R$ 11.26/MWh, with estimated funding of R$ 5.23 billion — a reduction of approximately 15% compared with 2025.
The CDE is subdivided into sub-items, the most important of which are: the Fuel Consumption Account (CCC), which compensates isolated systems for the use of high-cost fossil fuels for power generation; Incentivized Sources – Distribution Tariff Discounts; and Low Income – Social Electricity Tariff (TSEE). For 2026, the CDE budgetary forecast is approximately R$ 52.7 billion (an increase of about 7% compared with 2025), of which R$ 47.8 billion via CDE-Use.
It is estimated that more than thirty percent (30%) of the electricity bill is due to the cost of energy.
Both CDE and PROINFA are expected to continue at least until 2030, with potential adjustments over time in line with new public policies.
B. Tariff Flags
The main function of the Tariff Flags (green, yellow and red – levels 1 and 2, and the former water-scarcity flag) is to balance distributors’ costs of acquiring higher-priced energy, especially from thermal plants, which occurs more frequently in times of water crisis. The flags signal to the consumer, month by month, the real cost of electricity generation that will be charged, giving them the opportunity to adjust consumption if they so wish. The “Water Scarcity Flag”, instituted in 2021, ceased to be applied as from April 2022. laws No. 15,235/2025 and No. 15,269/2025 promoted a review of the rules and triggers for activation of the tariff flags.
C. Taxes
In addition to the tariff, the Federal, State, and Municipal Governments charge on the electricity bill PIS/COFINS, ICMS, and the Public Lighting Contribution, respectively. Of these, the ICMS is the tax with the greatest impact on the electricity bill, with rates varying depending on the state and municipality.
Federal Taxes: The Social Integration Program (PIS) and the Social-Security Financing Contribution (COFINS) are taxes levied by the Federal Government, which are intended for the worker and for the Federal Government’s social programs.
State Tax: The Tax on the Circulation of Goods and Services (ICMS) is a state tax. As provided in article 155 of the 1988 Brazilian Federal Constitution, the tax is levied on transactions relating to the circulation of goods and services, and each State and the Federal District are empowered to define its rates. Distributors are required to charge the ICMS directly in the electricity bill and transfer the amount to the State Government. It is the tax with the greatest impact on the electricity bill.
Municipal Tax: The Public Lighting Contribution (CIP) is provided in article 149-A of the Brazilian 1988 Federal Constitution, which establishes, among the powers of the municipalities, the power to provide on the form of collection and the tax base of the CIP, by means of a specific law approved by the City Council. Therefore, the Municipal Government is solely and exclusively responsible for services involving the planning, implantation, expansion, operation, and maintenance of public lighting facilities. In this case, the concessionaire only collects the public lighting contribution for the municipality. The respective amounts are transferred even if the consumer does not pay the electricity bill.
The taxes above are the main taxes levied on electricity bills and vary according to the location, depending on the municipality and the state.
In the Section below we will describe in further detail the taxes levied on the electricity bill of the taxpayers. We note, however, that those who wish to obtain the detailed values of each of the taxes and charges with rates and impact on the amount paid in the electricity bill may check them in the electricity bills or in the tables provided by the concessionaires on their websites, as determined by ANEEL.
II. SPECIFIC TAXATION ON ELECTRICAL ENERGY
II.I FEDERAL TAXES: Social Integration Program (“PIS”) and Social Security Financing Contribution (“COFINS”)
Power supply transactions are subject to the levy of PIS and COFINS at the combined rate of 9.25% (non-cumulative regime) on the transaction price.
A) Controversy regarding the crediting of contracted versus consumed energy
Legal entities subject to the non-cumulative regime may, in accordance with the legislation (Laws No. 10,637/2002 and No. 10,833/2003), deduct credits in relation to “electrical energy and thermal energy, including in the form of steam, consumed in the establishments of the legal entity”. The credit covers all premises of the company and applies only when the energy is paid to a legal entity domiciled in the country.
Until 2023 there were isolated CARF decisions admitting the crediting also of amounts paid by way of “contracted demand” (power reservation). This understanding was, however, superseded. In July 2023 the Superior Chamber of Tax Appeals decided that only energy effectively consumed generates the right to PIS/COFINS credits (Decision No. 9303-014.076).
The position was consolidated in CARF Precedent No. 224, approved on 26 August 2025 and effective as from 1 September 2025:
“For the purposes of calculating credits under the non-cumulative regime of the Contribution to PIS/Pasep and of COFINS, only electrical energy effectively consumed in the establishments of the legal entity shall be considered; other expenses such as the Contribution for the Costing of Public Lighting (COSIP) or contracted demand do not fall within this concept.”
In practice, companies may only credit PIS/COFINS on energy effectively consumed (meter readings in kWh) and not on the full invoice amount when it includes contracted demand or other charges. The understanding has binding effect in the federal administrative sphere, which must be followed during audits and trials by the Federal Revenue Secretariats and CARF.
B) Controversy Regarding the Exclusion of ICMS from the PIS/COFINS Calculation Base: Refund of Unduly Paid Amounts
In 2017 the STF decided that ICMS does not form part of the calculation base of PIS and COFINS (Theme 69 – the “Century Thesis”), with retroactive effects to 15 March 2017. Law No. 14,385/2022 regulated the refund to consumers of the ICMS amounts that had been unduly included in the calculation bases and subsequently refunded to distributors.
Dissatisfied, the electricity distributors filed Direct Action of Unconstitutionality (ADI) 7,324. On 14 August 2025 the STF upheld the constitutionality of Law 14,385/2022 and fixed a 10-year limitation period (article 205 of the Civil Code) for consumer claims.
Main consequences:
- Distributors are obliged to pass on to consumers the amounts refunded, in accordance with ANEEL regulation (compensation on invoices or other mechanisms);
- They may deduct taxes levied on the refund and specific legal fees of the case;
- The 10-year period is counted from the effective restitution of the undue amount to the distributors (or from the homologation of the compensation).
Official estimates indicate relevant amounts — approximately R$ 44.5 billion already passed on to distributors between 2021 and 2024 and approximately R$ 5.8 billion relating to 2025 — still to be returned to consumers through the invoice. The decision ended a long tax controversy and reinforced regulatory certainty in the sector.
II.II. Tax on the Circulation of Goods and on the Provision of Interstate and Intermunicipal Transportation and Communication Services (“ICMS”)
This is the tax with the greatest impact on the price of the Electricity Tariff (TE) and the one that most increases the electricity bill. Starting in 2022, the rates, which previously ranged from 18% to 32%, were reduced to values close to 18% in all states, due to the enactment of Complementary Law 194/22, which included electricity among the goods and services considered “essential and indispensable.”
II.II.1 TAX RATE
The internal ICMS rates on electrical energy are set by each state and vary by consumption band. As a rule, electrical energy rates were reduced in most States after Complementary Law 194/2022, which classified energy as an essential good. By way of example, the legislation of the States of São Paulo and Rio de Janeiro is detailed in the table below.
ICMS on electrical energy — São Paulo and Rio de Janeiro
| Sate | Category / consumption band | ICMS rate |
| São Paulo | Residential: up to 90 kWh/month | Exempt |
| Residential: 91 to 200 kWh/month | 12% | |
| Residential: above 200 kWh/month | 18% | |
| Electrified public passenger transport | 12% | |
| Rural establishment with agricultural or pastoral activity and state registration | Exempt* | |
| Other classes, including industrial and commercial | 18% | |
| Rio de Janeiro | Electrical energy: up to 300 kWh/month | 18% |
| Electrical energy: above 300 kWh/month | 20% + 4% FECP | |
| Electrified public passenger transport | 6%** |
* In São Paulo, although article 52, V, “d” of the RICMS-SP provides for a 12% rate, the more favourable exemption of article 29, I of Annex I currently prevails, in force until 31 December 2026. The residential exemption up to 90 kWh has the same validity.
** In Rio de Janeiro the 6% rate corresponds to ICMS proper. The FECP must also be considered: as a rule 2%, raised to 4% when consumption exceeds 300 kWh. Residential supply of up to 300 kWh is not subject to the additional charge.
Note on São Paulo. The formal provision of 25% for residential consumption above 200 kWh remains in the RICMS-SP but must not be applied after Complementary Law No. 194/2022 and STF Theme 745. In these transactions the general rate of 18% applies.
II.II.2. TAX BASE
II.II.2.A. INTRODUCTION
In general, the ICMS tax base shall correspond to the transaction price – result of the sum of all amounts and charges inherent in the provision of electrical energy for consumption, plus the applicable ICMS amount, which have been charged, on any account, from the person indicated as recipient in the tax document as a result of the performance of an electrical energy supply agreement entered into between such person and the distribution company.
However, electrical energy concessionaires also include transmission and distribution expenses (Transmission System Use Tariff – TUST and Distribution System Use Tariff – TUSD) in the ICMS tax base, in addition to the client’s consumption, and further add other charges passed on to third parties, which inflates the ICMS tax base.
As a result of this practice, there is discussion in the courts about the inclusion or exclusion of the TUSD and TUST tariffs in the ICMS tax base, the recent chapters of which are summarised below.
II.II.2.B Dispute about the Inclusion/exclusion of the Distribution System Use Tariff – TUSD and of the Transmission System Use Tariff – TUST in the ICMS tax base
TUSD (Distribution System Usage Tariff) is the consideration paid to the public-service concessionaire for the use of those electrical systems in the generation and consumption of energy. TUST (Transmission System Usage Tariff) is the tariff that remunerates the transmission system and is paid by users of the Basic Network of the electric power system: generators, distributors, free consumers, and traders that import and export electric energy. Both TUSD and TUST are charged to the electricity consumer, whether in the regulated environment or in the free contracting environment, and constitute consideration for the use of the system (“use of the wire”). These tariffs form part of the monthly costs of the National Interconnected System (SIN), which produces and transmits electric energy in the country.
TUSD and TUST remunerate the use of the distribution and transmission systems and are charged to the final consumer (captive or free). Since 2017 there has been controversy regarding their inclusion in the ICMS calculation base.
On 27 March 2017, in Special Appeal 1,163,020/RS, the 1st Panel of the STJ changed the previously dominant jurisprudence favourable to taxpayers by deciding in favour of the tax authorities and against the exclusion of TUST and TUSD from the ICMS calculation base, stating that it is not possible to dissociate the stages of energy supply.
Subsequently, on 13 March 2024, under the repetitive appeals procedure (Theme 986), the First Section of the STJ unanimously established that TUSD and TUST must be included in the ICMS calculation base for electrical energy in situations where they are charged on the electricity bill as a charge to be paid directly by the final consumer — whether free (one that can choose its own energy supplier) or captive (taxpayers who do not have that choice).
The thesis has binding effect. The modulation of effects preserved, until 27 March 2017, the preliminary decisions that benefited taxpayers (collection without inclusion of the tariffs). After that date, inclusion is mandatory, except in cases with a final and unappealable decision prior to that date or with a still-valid injunction under the specific conditions fixed by the STJ.
Complementary Law No. 194/2022, through its article 2, provided for the non-levy of ICMS on TUSD and TUST:
Art. 3. The tax shall not apply to:
(…)
X – transmission and distribution services and sectoral charges linked to operations involving electric energy. (Included by Complementary Law No. 194 of 2022)
However, in that same year (2022), several States filed Direct Action of Unconstitutionality (ADI) No. 7,195 before the STF, seeking a preliminary injunction, to challenge the constitutionality of the exclusion of TUST and TUSD from the ICMS tax base, pursuant to the new wording given by Complementary Law No. 194/22 to Article 3, item X, of Complementary Law No. 87/96. They alleged an invasion of state competence (Article 155, § 2, XII, “b”, of the 1988 Federal Constitution) and fiscal impacts in the billions of reais, also affecting municipal transfers. In a virtual session concluded on March 3, 2023, the Plenary of the STF upheld the preliminary injunction previously granted by the rapporteur, suspending the effectiveness of Article 2 of Complementary Law No. 194/2022.
The merits of ADI 7,195 remain pending before the STF. While the preliminary suspension remains in force, the inclusion of TUSD and TUST in the ICMS base is maintained, in line with the STJ thesis in Theme 986. Regional and state courts have followed this guidance.
It is noteworthy that the Supreme Federal Court (STF), in 2025 (Extraordinary Appeal No. 1,539,198/MT, judged on May 26, 2025), reaffirmed the infraconstitutional nature of the controversy — pursuant to General Repercussion Theme 956 — confirming that the competent court to decide the matter is the STJ and eliminating any residual controversy over the constitutional issue.
II.II.2.C ICMS on TUST/TUSD – National Jurisprudential Conclusion
The prevailing understanding is that TUST and TUSD form part of the ICMS calculation base when charged to the final consumer. Residual judicial discussion is limited to cases with an injunction or final and unappealable decision prior to 27 March 2017.
The State of São Paulo, for example, launched in 2025 a self-regularisation action aimed at consumers with debts relating to these amounts. Approximately 300 electricity consumers (both regular ICMS taxpayers and non-taxpayers such as hospitals, shopping centres and banks) were able to regularise their situation spontaneously and without penalties. According to the Sefaz-SP portal, by July 2025 more than R$ 204 million had been recovered through this initiative.
II.II.3 INTERNAL AND INTERSTATE ELECTRIC POWER DISTRIBUTION TRANSACTIONS IN THE STATE OF SÃO PAULO
With respect to internal and interstate transactions relating to the supply of electrical energy, we set out below comments on the applicable taxation.
Distributors sell and physically deliver energy to captive consumers. To free consumers they only deliver energy, but do not sell it. Therefore, these free consumers purchase energy directly from the generators or traders and pay them for the energy. For that reason, in principle, the generator or traders should be defined by law as ICMS taxpayers de jure.
II.II.3.A SCENARIO UNTIL 2021: JUDICIAL CHALLENGE ON TAX SUBSTITUTION OF DISTRIBUTORS
Since 2009, the State of São Paulo promoted, through Decree 54.177/09, a change in the ICMS Regulations, providing that the distributors should act as substitute taxpayers and pay the ICMS due by the generators or traders, in the event of sale of energy to the free consumers.
The Decree was challenged in the STF. Direct Action for the Declaration of Unconstitutionality (ADIn) 4281 was filed, which discussed the unconstitutionality of attributing to electrical energy distribution companies, by means of a decree, liability for the payment of ICMS levied on the sales of electrical energy carried out between traders and taxpayers of the State of São Paulo. Please note that this attribution of the capacity as substitute taxpayer of energy distributors resulted in an increase in the ancillary obligations and in the cost of compliance both to the energy distributors and consumers. The ADIN was granted in late 2020 by the STF, which acknowledged especially that only a law in the narrow sense (and not a decree) could transfer tax liability to third parties. The Court modulated the effects of the decision, and it produced effects only after publication of the Appellate Decision, for which reason the law of the State of São Paulo on electrical energy distribution transactions was subject to a deep and amendment in 2021, upon enactment of decrees 65.823/21 (already revoked) and 66.373/21, still in force.
II.II.3.B CURRENT SCENARIO: DECREE 66.373/21- São Paulo changes the ICMS payment system in transactions with Electrical Energy in the Free Contracting Environment (ACL)
The Decree revokes Exhibit XVIII to the ICMS Regulation of the State of São Paulo (RICMS-SP) and consolidates the rules on the matter in articles 425, 425-A to 425-H, and 426 of the RICMS-SP. Ordinance SRE 14/22 introduced the ancillary obligations relating to these provisions.
Currently, in light of the above, the collection of ICMS on electricity transactions in the Free Contracting Environment (ACL) in São Paulo has been significantly redefined by Decree 66,373/21 and Treasury Regulation (Portaria SRE) 14/22. The previous model, based on tax substitution by distributors and the mandatory use of the DEVEC (Declaration of Electricity Operations), has been abolished. Now, the responsibility for recording and paying the tax depends on the supplier’s origin: when the supplier (generator or trader) is based in São Paulo, it is responsible for including and collecting the ICMS on the Electronic Invoice issued to the São Paulo consumer. Conversely, if the supplier is located in another state, the responsibility falls to the consumer in São Paulo, who must obtain a state tax registration, issue an inbound invoice, calculate, and pay the ICMS through self-assessment, adhering to the deadlines set by tax legislation.
Additionally, there are specific rules for operations where the consumer is connected to the distribution network (in which case the distributor collects the ICMS related to the connection) or to the basic transmission network (where the consumer is responsible for the tax on network usage charges). The regime also allows adherence to a simplified tax regime for consumers or agents not originally subject to ICMS, provided specific requirements are met, although the use of tax credits is prohibited.
This new framework brings greater clarity, legal certainty, and alignment with recent judicial decisions, while also adapting São Paulo to the best fiscal compliance practices in the electricity sector.
Please see:
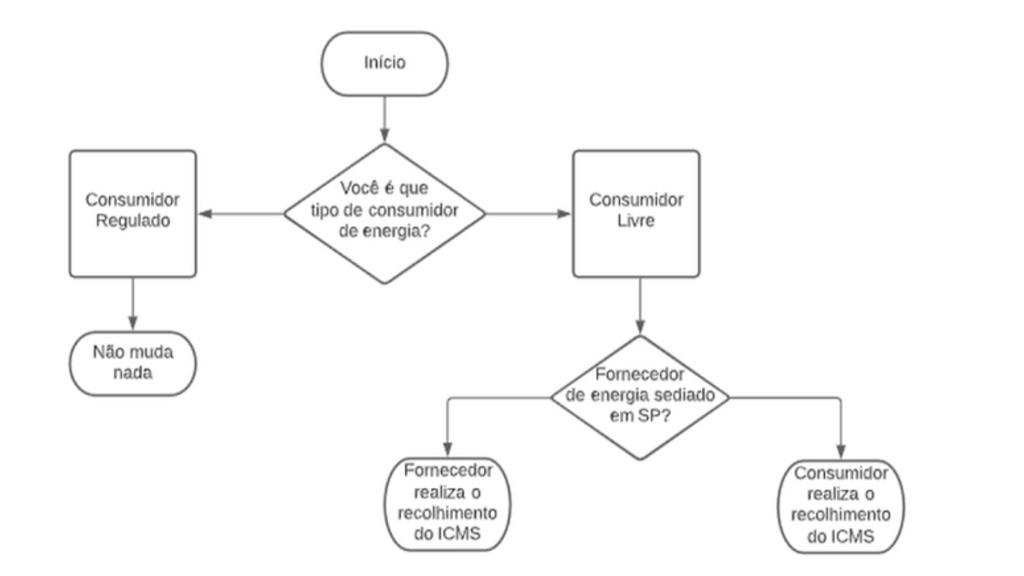
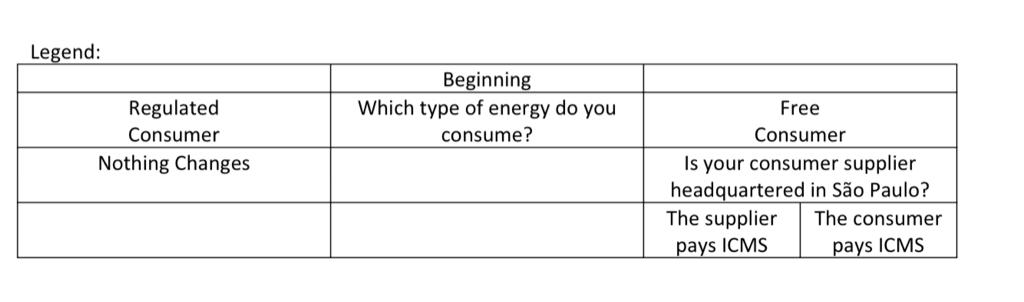
Key Points of the Flowchart
- Regulated Consumer (ACR): The flowchart accurately indicates that “nothing changes” — the ICMS model for regulated operations remains unchanged, with the distributor responsible for calculating and collecting the tax.
- Free Consumer (ACL):
- If the energy supplier (generator/trader) is based in São Paulo: The supplier is responsible for collecting and including the ICMS on the invoice.
- If the supplier is located outside São Paulo: The São Paulo consumer (recipient of the energy) is responsible for self-assessing and paying the ICMS, fulfilling specific accessory obligations, after obtaining a state tax registration when necessary.
This framework provides greater predictability, aligns with the STF’s decision in ADI 4281, and reduces disputes over tax substitution, making it crucial for companies in the ACL to ensure fiscal compliance in the state.
II.II.3. C Internal Electrical Energy Distribution Transactions – Tax Rates
In the State of São Paulo, as provided in article 52, item V of the RICMS-SP, the applicable rates are as follows:
- 12% in relation to residential accounts with monthly consumption of up to 200 kWh;
- 18% in relation to residential accounts with monthly consumption above 200 kWh;
- 12% when used in electrified public passenger transport;
- 12% in transactions with electrical energy used in a rural property that effectively maintains agricultural or pastoral activity and is enrolled in the ICMS Taxpayers’ Register.
Observation: after Complementary Law 194/2022 and the application of STF Theme 745, the rate on electrical energy in São Paulo does not exceed the general rate of 18%. In some low-consumption residential bands (up to 90 kWh) there may be exemption, in accordance with legislation and the practice of the concessionaires.
The rates may differ in other States. In the State of Rio de Janeiro, after the changes introduced as a result of Complementary Law 194/2022, the rates applicable to internal transactions with electrical energy became 18% for monthly consumption of up to 300 kWh and 20% for excess consumption, with a reduced rate of 6% when used in electrified public passenger transport.
II.II.3.D Electronic Energy Invoice (NF3-e) – New Deadlines and Obligations
The Electronic Energy Invoice (NF3-e, model 66) became mandatory in the State of São Paulo as from 1 October 2025, pursuant to Ordinance SRE No. 14 of 21 March 2025, together with the national schedule regulated by the applicable SINIEF Adjustments (including SINIEF Adjustment No. 03/2025).
This is a critical accessory obligation, requiring the accurate inclusion of taxes (ICMS/TUST/TUSD/PIS/COFINS), adherence to the layouts established by the State and Federal Revenue Services, and integration with the enterprise management systems of the involved agents, under penalty of tax audits and operational restrictions.
The NF3-e represents not only a fiscal and documentary obligation but also a true watershed moment for the standardization, traceability, and transparency of electricity operations in São Paulo, with significant implications from tax, accounting, operational, and regulatory perspectives.
II.II.4.Interstate Electrical Energy Distribution Transactions
Transactions involving the supply of electrical energy to individuals or legal entities in different States are not subject to the levy of ICMS, as provided in article 155, item X, letter “b” of the Brazilian Federal Constitution:
“Art. 155. It is incumbent upon the States and the Federal District to create taxes on:
X – it shall not be levied:
b. on transactions that send oil, including lubricants, liquid and gaseous fuels derived therefrom, and electrical energy to other States.”
The immunity, however, applies only if the electrical energy is used in the production of goods or in the provision of services intended for trading or industrialisation (article 2, § 1, item III of Complementary Law No. 87/96). If the energy is destined to a final consumer, the immunity does not apply.
The Federal Supreme Court, in RE No. 748,543 (Theme 689 of General Repercussion), decided that in an interstate transaction of supply of electrical energy only the State of destination is competent to collect ICMS from the final consumer that uses the electrical energy in the industrialisation process of products relating to its core activity. The State of origin may not levy the tax in these cases. The appellate decision became final and unappealable in November 2020 and must be observed in all proceedings on the matter.
In practical terms, when an industry purchases electrical energy from another State for use in its production process, only the State of destination (where the consuming company is located) may collect ICMS. This avoids double taxation and ensures that the tax benefits the State where consumption actually occurs.
With respect to interstate rates, the following apply pursuant to article 155, § 2, VII of the Federal Constitution and Senate Resolution No. 22/1989:
- 7% on transactions destined to the States of the North, Northeast and Central-West regions and to the State of Espírito Santo;
- 12% on transactions destined to the States of the South and Southeast regions (except Espírito Santo).
II.II.5. Simplified Tax Regime in the State of São Paulo
The Simplified Tax Regime for the assessment and payment of tax by recipients, when the taxpayer status arises exclusively from operations with electric energy, is provided for in Ordinance SRE No. 14/2022.
The Simplified ICMS Tax Regime in São Paulo, as provided in Articles 16 to 18 of Treasury Regulation (Portaria SRE) 14/2022 and Articles 425-B, 425-D, and 426 of the São Paulo ICMS Regulation (RICMS-SP), allows free consumers (or sellers, as applicable) to streamline specific accessory obligations in the acquisition of electricity exclusively for consumption, through a formal adhesion agreement, with the trade-off of not being able to claim tax credits for these operations.
The Simplified Regime essentially consists of the issuance of an NF-E (Electronic Invoice) and the collection of ICMS, exempting the taxpayer from submitting and delivering the ICMS Information and Calculation Guide – GIA/SP and the Digital Tax Bookkeeping – EFD ICMS-IPI. However, throughout the period during which the recipient is subject to said regime, the use of any credits of such tax shall be prohibited.
II.II.6. EXEMPTION AND TAX BENEFITS
II.II.6.1. Exemption to Rural Producers
There is exemption of ICMS, as provided in Confaz Convention 76/91, on the supply of electrical energy to rural establishments, upon satisfaction of the conditions (engage in agricultural or cattle-raising activities, be enrolled with the ICMS Taxpayers’ Register).
II.II.6.2. Benefits for GD – Distributed Generation – Modalities
There is an exemption granted by the States and the Federal District under ICMS Agreement 16/2015 for transactions with distributed generation under the Electrical Energy Compensation System (SCEE).
In the State of São Paulo, Decree 67,521/2023 amended article 166 of Annex I of the RICMS-SP, extending the ICMS exemption in internal electrical energy transactions carried out by microgenerators and minigenerators to other modalities of distributed generation and to solar photovoltaic generating plants with installed capacity of up to 5 MW. The São Paulo benefit has been extended until 31 December 2026 (Decree No. 69,287/2024), a period shorter than the federal regime, which requires normative monitoring regarding possible further extensions.
II.II.6.3 Progressive Taxation on Distributed Generation (WireB)
Law No. 14,300/2022 (Legal Framework for Micro and Mini Distributed Generation) instituted the progressive schedule for charging the “Wire B” component of TUSD on energy injected into the grid by micro and mini distributed generation systems subject to the new system (units without acquired right to the previous regime, which remains until 2045 for projects filed within the legal deadline), according to the table below:
| Year | % of Wire B charged |
| 2023 | 15% |
| 2024 | 30% |
| 2025 | 45% |
| 2026 | 60% |
| 2027 | 75% |
| 2028 | 90% |
| As from 2029 | Rule to be established by ANEEL |
In 2026 the percentage charged reaches 60% of the corresponding tariff component, directly impacting the profitability of the compensation model, especially for new projects. Detailed analysis of distribution and distributed generation contracts is recommended for the correct calculation of credits and taxes incident on the transaction.
II.III. MUNICIPAL TAX: PUBLIC LIGHTING SERVICE CONTRIBUTION
This municipal contribution is levied on electrical energy and is named CIP or COSIP, and its purpose is to pay for the municipalities’ public lighting services, improving the lighting of all public roads, squares, viaducts, roads, and tunnels, making them safer.
The CIP varies in accordance with the tax rates established by each municipality. As a general rule, the tax rates are related to the electricity load made available by the concessionaire and the type of consumer. The tariff is also charged to users benefiting from the new social tariff, covered in the next chapter, as long as there is recorded consumption.
III. Universal Free Market and Tax Implications from 2025
The universal opening of the free energy market was structured by Law No. 15,269/2025 (conversion of Provisional Measure No. 1,304/2025) and regulated by Decree No. 13,097/2026. Under the current schedule, industrial and commercial consumers served at low voltage may exercise free choice of supplier as from 25 November 2027, and the remaining consumers — including residential consumers — as from 25 November 2028.
This change impacts the system of collection of charges and taxes, requiring the enhancement of fiscal controls regarding the active liability for ICMS, PIS/COFINS (and, in the future, CBS/IBS), tax responsibility and reporting mechanisms to state and federal tax authorities. The new environment requires rigorous contractual analysis to avoid double taxation, ensure the correct appropriation of tax credits and adjust systems for the issuance of electronic tax documents for multiple agents.
IV. LAW No. 15,235/2025 AND LAW No. 15,269/2025 – IMPLICATIONS FOR THE STRUCTURE OF THE ELECTRICAL SECTOR
Provisional Measure No. 1,300/2025 was converted into Law No. 15,235/2025 (sanctioned on 8 October 2025), while the broader modernisation themes of the sector (including the opening of the free market) migrated to Provisional Measure No. 1,304/2025, converted into Law No. 15,269/2025 (published on 25 November 2025).
Among the main innovations the following stand out:
- Expansion of the Social Electricity Tariff (TSEE): Law 15,235/2025 now guarantees a full discount (100%) of the tariff for families enrolled in the CadÚnico with per capita income of up to half a minimum wage, for monthly consumption of up to 80 kWh. For consumption between 81 and 220 kWh the full tariff applies. The Social Discount was also created, consisting of exemption from the CDE for consumption of up to 120 kWh/month for families with per capita income between half and one minimum wage, in force as from 1 January 2026. The fiscal impact of the measure is estimated at more than R$ 4 billion per year, shared among the other consumers of the SIN, with repercussions on captive ICMS and sectorial quotas.
- Universalisation of access to the Free Energy Market (ACL): as detailed in Section III, with the schedule regulated by Decree No. 13,097/2026, which in turn regulates Law 15,269/2025. Schedule: 25 November 2027 for industrial and commercial low-voltage consumers; 25 November 2028 for the remaining consumers.
- Creation of the Supplier of Last Resort (SUI): regulated agent responsible for the supply of energy to consumers that do not migrate to the ACL and are not bound by regulated-environment contracts.
- Review of the tariff flag regime: new rules and activation triggers, with more sensitive signalling of generation costs.
- Temporal limitation of TUST/TUSD discounts for incentivised sources: only projects with grants and contracts entered into by the legal deadlines maintain the right to the tariff discounts during the initial term; extensions or renewals with maintenance of the same incentives are prohibited. This restriction requires detailed fiscal assessment of incentivised generation projects and directly influences the tax planning of companies in the segment.
- Sharing of sectorial charges: adjustments in the Energy Development Account (CDE), with potential alteration of the base for passing on taxes and charges in the final consumer tariff, with direct impact on the calculation of ICMS, PIS/COFINS and, in the future, IBS/CBS.
V. Law 15,103/2025 (PATEN) – Tax Incentives and Financial Instruments for the Energy Transition
Law No. 15,103 of 22 January 2025 instituted the Program for the Acceleration of the Energy Transition (PATEN), structuring a framework of tax incentives and financial instruments to leverage investments in the modernisation of the energy matrix, renewable energy generation, energy efficiency and technological innovation.
Among its main tax-related innovations is the possibility of using tax credits, including court-ordered payment rights (precatórios), as collateral for financing related to PATEN-certified projects through the Green Fund, as well as the creation of sustainable tax-settlement mechanisms. The law further provides that amounts not allocated to PATEN projects by the end of each financial year must be transferred to the Energy Development Account (Conta de Desenvolvimento Energético — CDE), thereby indirectly contributing to tariff affordability.
Law No. 15,103/2025 therefore serves a dual purpose: it enables structural investments aimed at the technological development of the electricity sector and, at the same time, introduces innovations in compliance and sustainable tax-settlement mechanisms, marking a new stage in the alignment between fiscal policy, energy-transition objectives and tax fairness.
The operationalisation of PATEN depends on federal regulation (Ministry of Mines and Energy and BNDES) regarding project approval criteria, the functioning of the Green Fund and certification processes. Monitoring of the first calls for proposals is recommended.
In the same field of energy transition, the following should be noted:
- Law No. 14,948/2024, which instituted the legal framework for low-carbon-emission hydrogen, and Law No. 14,990/2024, which created the Low-Carbon-Emission Hydrogen Program (PHBC) and granted R$ 18.3 billion in PIS/Cofins tax credits for the production and purchase of low-carbon-emission hydrogen, to be operationalised by competitive auction, with validity in the 2028–2032 cycle;
- Law No. 15,097/2025, which instituted the regulatory regime for offshore wind generation, with guidelines for the assignment of use of aquatic spaces, environmental licensing and project implementation schedule — a relevant investment vector for companies in the submarine transmission and wind-farm segment, with regulation still under development.
- Decree No. 13,096/2026, which regulated the legal framework and the National Low-Carbon Hydrogen Policy, providing greater certainty for the implementation of the instruments established by Laws No. 14,948/2024 and No. 14,990/2024; and
These legal instruments reinforce the importance of renewable energy projects, low-carbon hydrogen, electricity infrastructure and offshore energy development within Brazil’s energy-transition agenda. However, project feasibility will depend not only on tax incentives, but also on regulatory, environmental, land-use, grid-connection and financing considerations.
VI. 2025 TAX REFORM AND ITS EFFECTS ON ELECTRICITY TAXATION
The Tax Reform, consolidated mainly by Constitutional Amendment No. 132/2023 and Complementary Law No. 214/2025, introduced significant structural changes in the taxation of the Brazilian electrical sector, with direct effects on the incidence and calculation base of the taxes levied on electrical energy.
Complementary Law 214/2025 operationalised the new taxes: the Goods and Services Tax (IBS), of subnational competence, and the Contribution on Goods and Services (CBS), of federal competence, which replace PIS/COFINS, ICMS and ISS in the consumption chain.
The constitutional transition schedule (ADCT, arts. 125 et seq.) is as follows:
| Phase | Period | Main events |
| Test phase | 2026 | Collection of symbolic rates (CBS 0.9% and IBS 0.1%), compensable, for system adaptation; full coexistence with the current regime |
| Effective start | 2027 | Full collection of CBS; extinction of PIS and COFINS; reduction of IPI to zero (except products with incentivised industrialisation in the Manaus Free Trade Zone) |
| ICMS/ISS transition | 2029-2032 | ICMS and ISS rates reduced to 90% (2029), 80% (2030), 70% (2031) and 60% (2032) of the reference rates; IBS increases gradually |
| Full effectiveness | 2033 | Extinction of ICMS and ISS and of state and municipal tax benefits; full collection of IBS and CBS |
During the transition period, accumulated credits from the taxes to be phased out may be offset or refunded, subject to the applicable constitutional, legal and regulatory provisions. For the electricity sector, the transition requires particular attention to the adaptation of systems, tax documents, contracts and billing flows involving generators, traders, distributors, transmission companies and consumer.
VI.1.Structural Rules Applicable to the Electricity Sector
The application of IBS and CBS to electricity transactions is governed by Article 28 of Complementary Law No. 214/2025, as amended by Complementary Law No. 227/2026. The legislation establishes specific rules on taxation and liability for payment that are consistent with the regulatory structure of the electricity sector.
- Collection in the Regulated Contracting Environment (ACR): electricity distribution companies are responsible for collecting IBS and CBS on electricity supplied to purchasers served in the Regulated Contracting Environment (Ambiente de Contratação Regulada — ACR).
- Charges for use of the distribution network in the Free Contracting Environment (ACL): distribution companies are also responsible for collecting the taxes levied on charges for the use of distribution systems by consumers served in the Free Contracting Environment (Ambiente de Contratação Livre — ACL).
- Electricity purchases in the ACL: in electricity acquisitions intended for consumption by the purchaser in the ACL, the seller is generally responsible for collecting the taxes. The legislation also establishes specific situations in which the consuming establishment itself may be liable for payment.
- Transmission and connection to the Basic Grid: the transmission company is responsible for collecting IBS and CBS on transmission and connection services provided to consumers directly connected to the Basic Grid.
- Distributed generation: electricity supplied by a distribution company in an amount corresponding to the electricity injected into the grid by the consumer unit itself remains excluded from the IBS and CBS taxable basis, subject to the applicable net-metering rules.
- Destination-based taxation: IBS and CBS follow the destination principle, which is consistent with the approach already applicable to ICMS on electricity transactions.
The new framework will require electricity sector participants to adapt contracts, billing systems, tax documents and compliance controls, particularly in ACL transactions. The operational aspects of the new rules should be monitored in light of supplementary regulations and procedures issued in connection with the implementation of the Brazilian Tax Reform.
These changes form part of the modernisation of the Brazilian tax system and are expected to impact the electrical sector positively, provided they are accompanied by adequate regulation by ANEEL and the government, so as to avoid tax overlap and legal uncertainty.
VII. Federal and Regional Incentives — REIDI, SUDENE and SUDAM and Complementary Law No. 224/2025 in the electrical sector
The Brazilian incentive framework applicable to infrastructure and energy projects includes, among others, the Special Incentive Regime for Infrastructure Development (Regime Especial de Incentivos para o Desenvolvimento da Infraestrutura — REIDI), the regional incentives administered by Sudene and Sudam, and instruments aimed at supporting the energy transition. These regimes should be assessed jointly with Complementary Law No. 224/2025, which reduced certain federal tax, financial and credit incentives and benefits.
The reduction does not necessarily apply uniformly to all incentives. Complementary Law No. 224/2025 establishes different rules depending on the nature of the benefit — including exemptions, zero rates, reduced rates, reductions in the taxable basis, presumed tax credits and reductions of tax due. Accordingly, the economic impact must be assessed on a case-by-case basis, considering the specific incentive, the project implementation timeline and any conditions already satisfied by the taxpayer.
| Regime | Legal basis | Main benefit | Observation following Complementary Law No. 224/2025 |
| REIDI | Law No. 11,488/2007 | Suspension of PIS/Cofins on the acquisition and importation of goods and services intended for qualifying infrastructure projects | The impact of Complementary Law No. 224/2025 should be assessed according to the nature and specific rules of the incentive applicable to each project |
| Sudene | Complementary Law No. 125/2007 | Reduction of Corporate Income Tax (IRPJ) for projects implemented, expanded, modernized or diversified within its area of operation | The application of the incentive reduction depends on the type of benefit and the specific circumstances of the project |
| Sudam | Complementary Law No. 124/2007 | Reduction of IRPJ for projects located in the Legal Amazon region | The application of the incentive reduction depends on the type of benefit and the specific circumstances of the project |
The preservation of benefits for projects that have already fully complied with burdensome conditions, or that are covered by transition rules, should be assessed individually. For investments in generation, transmission, storage, hydrogen and related infrastructure, the combination of REIDI, regional incentives, PATEN and other financing instruments remains relevant, but requires a prior assessment of eligibility, implementation timeline and the impact of legislative changes.
The combination of REIDI, regional incentives, PATEN instruments and programmes aimed at low-carbon hydrogen may represent a relevant source of financial efficiency for generation, transmission and energy-transition projects, provided that the applicable legal and regulatory requirements are met.
VII.VI. Sustainability and Reporting — CBAM and Disclosure Standards
The European Carbon Border Adjustment Mechanism (CBAM) entered its definitive phase in 2026, with the obligation to purchase certificates postponed to February 2027; although electricity is in a phase of scope expansion, groups with electrical assets in Brazil that export to the European Union must measure the carbon intensity of the energy used. In the Brazilian corporate sphere, the disclosure of sustainability reports according to the IFRS S1/S2 standards (CVM Resolution No. 193/2023) was converted into a voluntary regime by CVM Resolution No. 244/2026, with adoption of the “comply or explain” model as from 2027 for publicly-held companies.
VIII. CONCLUSION
The taxation of electrical energy in Brazil combines sector-specific rules (PIS/COFINS, ICMS, sectorial charges and CIP) with the process of opening the free market and the transition of the Tax Reform (IBS/CBS). The main changes of 2025-2026 — especially the universalisation of the Free Contracting Environment, the consolidation of jurisprudential theses (STJ Theme 986, CARF Precedent 224, ADI 7,324) and the deferral rules of Complementary Law 214/2025 — reshape the compliance and cost scenario for agents in the chain.
In the short term, particular attention should be given to the rules on liability for the collection of IBS and CBS in the electricity sector, the revision of federal incentives introduced by Complementary Law No. 224/2025, and the progressive regulation of instruments aimed at low-carbon hydrogen and the energy transition.
The present chapter presents the updated panorama as of 25 August 2026. Operational issues, project structuring and analysis of concrete cases should be assessed in light of the legislation and case law in force at the time of the transaction.
Authors: Sabine Ingrid Schuttoff / Claudia Derenusson Riedel / Camila Santana
De Luca, Derenusson, Schuttoff & Advogados – DDSA
Rua James Joule, 92 – 6th floor – Brooklin
04576-080 – São Paulo – SP
Phone: +55 (11) 3040 4040